Medicaid Crisis Planning FAQs
Answers When Your Family Needs to Make Decisions Quickly
When a loved one suddenly needs nursing home care, families often have more questions than answers. How will we pay for care? What happens to the house? Is it too late to protect assets? What should we do first?
Medicaid Crisis Planning can help you understand your options and make informed decisions, even when a loved one is already in a nursing home or needs long-term care soon.
Here are answers to some of the questions families ask us most often.
You Have Questions. We Have Answers.
Families in crisis often need clear answers first. Here are come of the most common questions we hear.
Can I keep my home?
In many cases, yes. Owning a home does not automatically prevent someone from qualifying for Medicaid. New York Medicaid rules include important exemptions and planning strategies that may allow you or your family to protect the home.
Every situation is different, however. Who owns the home, who lives there, marital status and other financial circumstances can all matter.
Before selling, transferring or making other decisions about a home, talk with an attorney who understands Medicaid planning. Don’t assume the house has to be sold simply because nursing home care is needed.
Is it too late?
Not necessarily. Planning ahead generally provides more options, but needing nursing home care does not mean that all planning opportunities have disappeared.
Even if your loved one is already in a nursing home, there may still be legal strategies available to protect some assets and help establish Medicaid eligibility.
The important thing is to act quickly and avoid making financial decisions before you understand their potential consequences.
Will my spouse keep our assets?
New York Medicaid rules include protections for the spouse who continues to live in the community. Depending on your circumstances, the community spouse may be permitted to retain certain assets and income rather than having everything spent on nursing home care.
The rules can be complicated, and the way assets are owned can make a significant difference.
Before spending down savings or transferring assets, have your situation reviewed so you understand what your spouse may be entitled to keep.
How quickly do I need to act?
As soon as possible.
A Medicaid crisis can develop quickly, particularly when someone is hospitalized, discharged to rehabilitation or told that Medicare or insurance will soon stop paying for care.
The sooner you understand your options, the more opportunity you may have to protect assets, gather the necessary documentation and avoid decisions that could complicate Medicaid eligibility.
You do not need to wait until a nursing home bill arrives to ask for help.
What is the Medicaid five-year lookback period?
When someone applies for nursing home Medicaid, certain financial transactions made during the previous five years may be reviewed. This is commonly referred to as the five-year lookback period.
Transfers or gifts made during that period can potentially affect Medicaid eligibility.
That does not mean you should try to undo transactions, move money or transfer property on your own. If you are facing a Medicaid crisis, an attorney can review what has occurred during the lookback period and explain what it means for your particular situation.
What happens if my parent is already in a nursing home?
It may still be possible to plan.
A nursing home admission can make the situation more urgent, but it does not necessarily eliminate opportunities to qualify for Medicaid or protect assets.
The first step is understanding your parent’s financial circumstances, the cost of care, how the care is currently being paid for and whether there are Medicaid planning strategies still available.
This is exactly the type of situation in which Medicaid Crisis Planning may be helpful.
Does Medicare pay for nursing home care?
Medicare may cover qualifying skilled nursing or rehabilitation care for a limited period under certain circumstances, but it generally does not provide ongoing coverage for long-term custodial nursing home care.
That distinction can surprise families. A loved one may enter rehabilitation with coverage and then learn that the coverage is ending while nursing home care is still necessary.
That is often when a Medicaid planning conversation becomes urgent.
How much does nursing home care cost in New York?
Nursing home care can cost thousands of dollars each month, and costs vary considerably depending on the facility, location and level of care required.
For families paying privately, those expenses can quickly consume savings that took a lifetime to accumulate.
Medicaid Crisis Planning looks beyond simply paying the next bill. The goal is to understand whether Medicaid may be available and what lawful planning options may exist to protect assets.
What assets can I keep and still qualify for Medicaid?
Medicaid eligibility does not necessarily require a family to give up everything it owns.
Different rules can apply to a home, retirement accounts, personal property, income and assets belonging to a spouse. Certain assets may be exempt or receive different treatment under Medicaid rules.
Because eligibility requirements and individual circumstances vary, the important question is not simply “How much money do I have?” It is “How will Medicaid treat the assets and income that I have?”
Can I give away or transfer assets to qualify for Medicaid?
Be very careful.
Giving money to children, transferring a home or moving assets shortly before applying for nursing home Medicaid can have unintended consequences because of Medicaid’s transfer and lookback rules.
A transaction that seems like an obvious solution could potentially delay eligibility.
Before giving away, transferring or retitling significant assets, speak with an attorney who can explain how the proposed action could affect Medicaid eligibility.
How long does the Medicaid application and approval process take?
There is no single timeline that applies to every case. The process can depend on the applicant’s circumstances, the completeness of the documentation, the complexity of the financial history and whether additional information is requested during review.
That is one reason preparation matters. Gathering financial and legal information early and submitting a complete application can help avoid unnecessary complications.
If your family is already facing nursing home expenses, don’t wait for the application process to become urgent before getting started.
What information will I need to apply for Medicaid?
A Medicaid application typically requires substantial financial and personal documentation.
Depending on the circumstances, that can include information about bank and investment accounts, income, retirement accounts, real estate, insurance, trusts, transfers and other financial transactions.
For a family already dealing with a hospitalization or nursing home admission, gathering everything can feel overwhelming. Part of the Medicaid Crisis Planning process is helping identify what is needed, organizing the information and addressing potential issues before or during the application process.
What happens when Medicare or insurance stops paying for services?
This is a common point at which families suddenly find themselves in a crisis.
A loved one may enter a rehabilitation facility following a hospitalization and then learn that Medicare or other insurance coverage is ending. If that person cannot safely return home, the family may suddenly be responsible for the cost of continued nursing home care.
That is a good time to call, and preferably before coverage actually ends.
An attorney can help you understand the transition from short-term coverage to long-term care and determine whether Medicaid planning may be appropriate.
If the nursing home offers to help with Medicaid, do I still need my own attorney?
It is important to understand who is representing whom.
A nursing home may help with the Medicaid application or refer you to someone who can assist with the process. That can be useful, but the nursing home’s primary concern is making sure the facility is paid for the care it provides.
Your attorney has a different role. Your attorney represents you and your family. That means looking beyond the application itself to identify opportunities to protect assets, evaluate planning strategies and help you make decisions based on your interests.
Before signing documents, transferring assets or making significant financial decisions, consider speaking with an attorney whose responsibility is to you.
What does a Medicaid Crisis Planning attorney actually do?
Medicaid Crisis Planning is about much more than completing an application.
An experienced attorney can review your family’s financial and legal circumstances, explain Medicaid eligibility requirements, identify potential problems, develop lawful strategies for protecting assets and help determine what needs to happen next.
When appropriate, the attorney can also assist with preparing the Medicaid application, responding to requests for additional information and helping your family navigate the process.
Most importantly, you have someone looking at the whole situation from your family’s perspective, rather than trying to figure it out on your own.
You Don't Have to Figure This Out Alone
If someone you love needs nursing home care now or may need it soon, the best time to understand your options is before making major financial decisions.
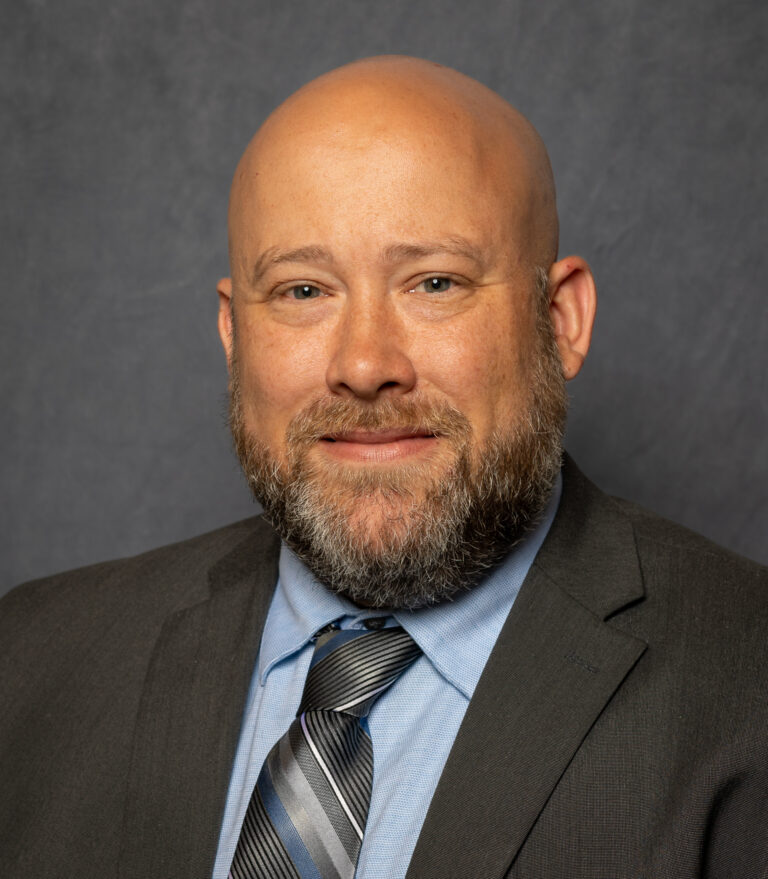
John C. Florsch, IV, Senior Counsel at RLGC Law Group, works with individuals and families facing Medicaid and long-term-care decisions.
Protect your family. Protect your assets. Know your options.
Schedule a consultation with John today. He is ready to take your call day or night, weekdays and weekends. 518-313-0379
- Decades of Experience in elder law and Medicaid
- Compassionate, Personalized Advice for your unique situation
- Focused on Protecting Your Family and Your Future
PRACTICE AREAS
- Medicaid Crisis Planning
- Elder Law
- Estate Planning
- Special Needs Planning
RESOURCES
- FAQs
- Guides & Articles
- Videos
- Webinars
CONTACT
- Albany, NY
- 518-250-4264
- info@rlgclaw.com
© 2050 RLGC Law Group. All rights reserved.
- Privacy Policy
- Terms of Service
- Cookies Settings